BoE’s Lombardelli: UK’s low-hire, low-fire labour market creating problems

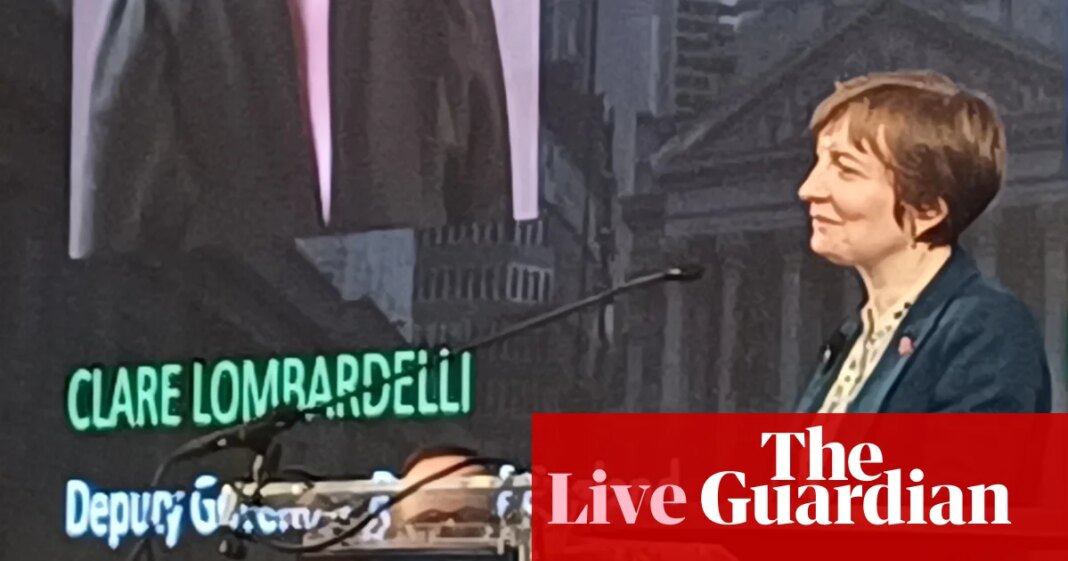
Now, the Bank of England Watchers conference is about to hear from the BoE’s deputy governor, Clare Lombardelli.
She starts by talking about the UK’s labour market – which is cooling, but through “less hiring rather than more firing.”
Expounding on points she made in her interview with the Guardian this morning, Lombardelli explains:
The economy has been more resilient to the recent energy cost shock than expected.
Activity has held up better than anticipated, unemployment has risen only gradually, and redundancies remain relatively low. That may sound like good news. In lots of important ways, it is.
But a low-hire, low-fire labour market creates its own problems. It protects those already in work while making it much harder for those trying to get in or move on.
This, Lombardelli explains, creates three challenges for the Bank of England:
-
First, it affects how the Bank of England interpret the rise in unemployment. “If those looking for work are poorly matched to the jobs available, higher unemployment may do less to ease wage pressures than it has in the past,” she says.
-
Second, it can weaken productivity and growth – it’s harder for workers to find job opportunities.
Lombardelli says “The costs are falling particularly heavily on young people, for whom the first step into work has become harder.”
-
Third, it can make the economy less able to adapt.
Key events
Onto questions!
Q: Why has the UK labour market showed resiliance, despite recent economic shocks?
Clare Lombardelli suggests the Bank may be “systematically underestimating” the economy’s ability to respond to shocks.
The BoE’s economic models may underestimate the ability of companies, and households, to react.
Another possibility is that the economy’s resilience is being eroded – with companies eating into their profit margins, and households running down their savings.
Lombardelli:
Clare Lombardelli then turns to UK interest rates.
She explains that the Bank of England is continuing to learn about the size of the energy shock from the Iran war, and the way it is passing through the economy.
She tells her audience here at the BoE Watchers conference:
Since our assessment in July the energy price shock has proved larger and more persistent.
That has increased the direct pressure on inflation, raised the prospect of greater indirect effects as higher costs pass through supply chains, and increased the risk of second round effects through wages, prices and inflation expectations.
That led the Bank to raise interest rates to 4% last week.
And looking ahead, Lombardelli explains that she believes the balance of risks to inflation remains to the upside.
And signalling that she could vote for another rate rise at future meetings, she says:
In the absence of evidence of weaker inflation pressures, I continue to think there is likely to be a case for a further increase in rates in the near term.
But, this decision will depend on how the Middle East conflict plays out, and how it affects price and wage setting across the economy, she concludes.
[that also fits with what she told my colleague Richard Partington in his article today]
Four reasons UK youth employment deteriorating faster than elsewhere
The UK labour market is behaving very differently for young people than it is for the wider population, Clare Lombardelli then warns.
She cites data showing that youth unemployment is unusually high in the UK, when compared to unemployment among prime-age workers.
That gap has widened over time, she points out, and faster than in other advanced economies
Lombardelli says four factors help to explain why job opportunities for young people in the UK have deteriorated by more relative to the national labour market than in other countries.
The first is the “low-hire low-fire” pattern we’re seeing in the UK economy.
But there are three more:
-
the concentration of weaker hiring in sectors that employ many young people;
-
the deterioration in young people’s health;
-
the rising cost and perceived risk of employing inexperienced workers.
On the drop in vacancies in industries that have traditionally relied on young people, Lombardelli says:
There is a relative undersupply of jobs in the accommodation, wholesale and retail sectors – the parts of the labour market with the highest concentration of inexperienced job seekers.
Those industries matter because they provide many of the starter jobs through which young people acquire workplace skills and start to build an employment history
Young people are bearing the greatest cost from the changes in the UK jobs market, BoE deputy governor Clare Lombardelli continues.
She produces data showing that that the UK’s youth unemployment rate is now more than three times the aggregate rate, its highest relative level since the early 1990s.
Lombardelli tells the Bank of England watchers conference:
Despite accounting for only around 12.5% of the labour force, 16 to 24-year-olds account for more than half of the rise in aggregate unemployment since mid-2022
Health
Clare Lombardelli then turns to the “unusual stability” in the jobs market.
Basically, people are moving jobs less often – be that into, out of, or between jobs.
She says that there is a clear downward trend in the data:
Thirty years ago, more than 3% of employed people changed jobs each quarter. Over the past year, the quarterly rate has been a little above 2%.
This is not too far off global financial crisis lows despite much less cyclical weakness.
Clare Lombardelli then reminds her audience that there were widepread shortages of workers after the Covid-19 lockdown – which may still have repercussions today.
She says:
As the economy reopened from the pandemic, acute labour shortages were widespread. The furlough scheme and wider fiscal and monetary support prevented large-scale unemployment. The rapid expansion in demand then left firms struggling to attract the skills they needed.
Bank Agency intelligence and a range of business surveys repeatedly reported acute recruitment difficulties and skills shortages, leading many firms to place a high value on retaining experienced staff.
Memories of recent labour shortages may have led employers to be more hesitant to make workers redundant, concerned that they will struggle to find the skills they need when activity recovers.
That leads to the ‘low-fire’ labour market she is concerned about, with a consequential ‘low-hire’ knock-on effect too!
BoE’s Lombardelli: UK’s low-hire, low-fire labour market creating problems
Now, the Bank of England Watchers conference is about to hear from the BoE’s deputy governor, Clare Lombardelli.
She starts by talking about the UK’s labour market – which is cooling, but through “less hiring rather than more firing.”
Expounding on points she made in her interview with the Guardian this morning, Lombardelli explains:
The economy has been more resilient to the recent energy cost shock than expected.
Activity has held up better than anticipated, unemployment has risen only gradually, and redundancies remain relatively low. That may sound like good news. In lots of important ways, it is.
But a low-hire, low-fire labour market creates its own problems. It protects those already in work while making it much harder for those trying to get in or move on.
This, Lombardelli explains, creates three challenges for the Bank of England:
-
First, it affects how the Bank of England interpret the rise in unemployment. “If those looking for work are poorly matched to the jobs available, higher unemployment may do less to ease wage pressures than it has in the past,” she says.
-
Second, it can weaken productivity and growth – it’s harder for workers to find job opportunities.
Lombardelli says “The costs are falling particularly heavily on young people, for whom the first step into work has become harder.”
-
Third, it can make the economy less able to adapt.
Cunliffe: A correction is coming….
Q: Is the world heading toward a financial crisis, and can we get out of it?
Sir Jon Cunliffe (who was a senior member of HM Treasury during the 2008 crisis), tells the Bank of England and its Watchers conference that a market correction is coming.
He says:
To me it’s pretty clear that a correction will happen.
The issue isn’t whether it’s coming, it’s whether it transmits though the financial system.
Cunliffe – a former Bank of England deputy governor – explains that policymakers normally worry when they see leverage involved in a boom.
Cunliffe’s “two poles” are the dotcom bust of 2000 – which inflicted losses on asset holders without creating a financial crisis – and the sub-prime crisis of 2008, which did ripple out into a financial crisis.
The difference between those two events is the interconnection and leverage. And it looks more and more that there is interconnection and leverage this time, Cunliffe cautions.
A mrket crash could lead to a credit crunch where everyone sells everything they can, Cunliffe continues. And if that happens, the tools a central bank would use look like the tools you’d use for other crises, he adds.
Nvidia faces a “difficult road ahead”, warns Niall Hearty, partner and regulatory lawyer at legal firm Weightmans:
“Shareholder lawsuits and an independent internal investigation will mean a difficult road ahead for the world’s second-largest company, particularly as Nvidia faces wider pressure from investors amid growing concerns around AI investment and the future of the sector.
There are also wider questions to be asked about national security and the protection of commercially sensitive information at a time when the US and China are racing to gain technological supremacy.”
Q: The Americans showed valuable leadership after the 2008 crisis – do you have confidence that if there is another major crisis the US would exercise leadership again? And would they be followed?
Professor Sir David Osmand tells the Bank of England and its Watchers conference there are two kinds of crisis.
“If the financial windows have been blown in,” he expects the US to step up, as it would be in their interest.
He’s more worried about a “slowburn crisis” – such as unregulated tokenisation.
There, the interests of the US may diverge from other countries, such as those in Europe, Osmand explains.
Spencer Dale, professor of practice at the London School of Economics, says the development of AI is likely to be the most significant source of risk.
The world has “completely failed” to agree any global response to AI, or agree a regulatory response, he says.
Instead, at points of stress – such as the risks from the Mythos AI model – the US has moved the other way, keeping information to itself.
Dale explains:
“Thus far I am not hugely comforted by the way the world has responded to the need to think about and talk about, and then sensibly regulate, AI at a global level.”
George Osborne: UK has opportunity to lead crypto world
Lauren Almeida
Over at the Digital Asset Summit in London, the former chancellor George Osborne is wearing one of his many hats as adviser to the crypto exchange Coinbase.
Osborne, who also recently joined the ChatGPT developer OpenAI, has suggested that the UK has the opportunity to be a leader in crypto innovation after the US mid-term elections, my colleague Lauren Almeida reports.
He said:
“The UK often has opportunity historically when the US system… can be more bureaucratic and fails to take advantage of a financial innovation.”
His comments come as the crypto industry frets over a less friendly environment in the US, where president Donald Trump’s control has been weakened by the midterm election result. His government had taken “pretty decisive steps forward on crypto regulation”, Osborne said.
Trump himself has been particularly bullish on the sector, having vowed to make the US the “crypto capital of the world” and pushed for deregulation of the industry. Last year he pardoned Changpeng Zhao — founder of the recently hacked crypto exchange Binance — who had been jailed after pleading guilty to failing to protect against money laundering.
That is not to mention Trump’s personal wealth in the sector — he made at least $1.4bn from his crypto ventures last year, according to financial disclosures he made in June.
But Osborne added that it was “too soon to know exactly what is going to happen” with the US approach to the sector.
“It is a bit simplistic to say Democrats are anti innovation in finance and Republicans are pro innovation in finance. There are [Democrats] who have led the case for innovation in the space.”