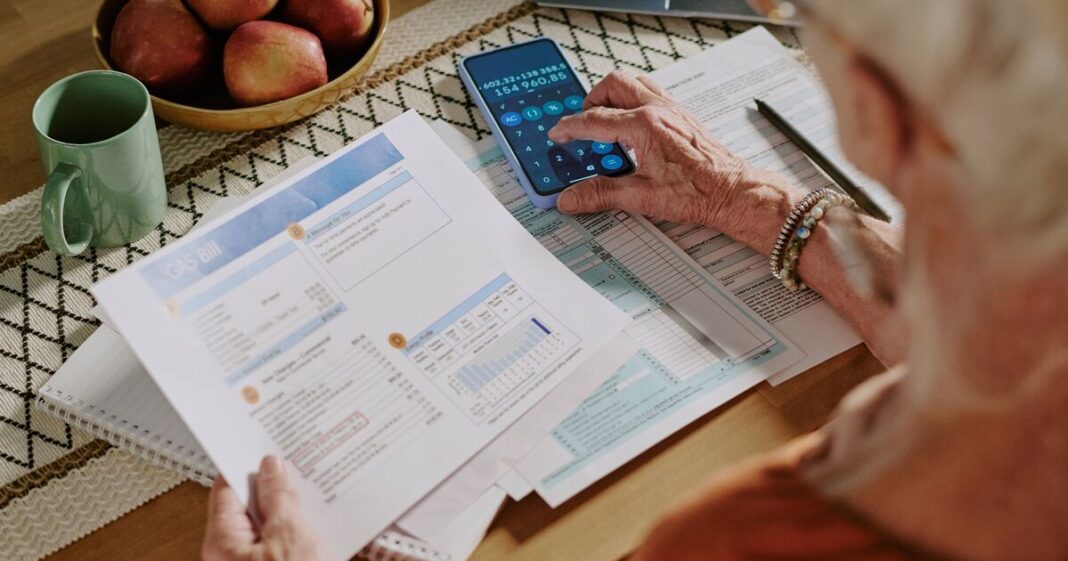

Sharon said she was left ‘overwhelmed’ (Image: AnnaStills via Getty Images)
When a Surrey woman lost her husband four years ago, she unexpectedly found herself dealing with bereavement while tackling unfamiliar financial documentation, pension choices and administrative duties.
“My husband did most of the financial planning,” Sharon, who preferred not to give her surname, told Skipton Building Society. “We always agreed it, but he was the one who would look out for the best place to do savings.
“When you lose somebody, you’re not really thinking about money. But you’re bombarded, truly bombarded, with letters, calls, emails.
“When all of a sudden you have two lots of finances and you’re looking at that, it’s quite overwhelming, to be honest with you. That was the first time I felt a little bit scared.”
The concerns occupying Sharon’s thoughts as she contemplated managing her financial future independently included “What do I do with this? Where do I put it? What is the best place to put it?”. Another unanticipated obstacle then emerged.
Her husband’s employer approached Sharon regarding an approximately £500,000 pension and death-in-service benefit which she had previously been unaware of, providing her with merely six months to determine what should become of the funds.
She said: “I remember I’ve been thinking, gosh, you know, I’ve got no idea. I just remember it being quite scary when you’ve got a chunk of money that you have to do something sensibly with when your mind is probably not in a very sensible way.”
The conversations that supported her
Fortunately, Sharon already had support available. Having started working with Skipton’s financial advice service in 2020, she had begun to develop her grasp of financial matters and knew where to seek assistance when she most needed it.

Sharon turned to Skipton Building Society for help (Image: Alamy/PA)
The pension was initially transferred into a pension arrangement and, following subsequent discussions regarding forthcoming rule changes and Sharon’s intentions for the funds, additional planning was implemented to name their two godchildren as beneficiaries.
She said: “I said, yeah, let’s just do that. So that took a weight off of my mind really, because, you know, you have got to make sure what you’re committing to.”
What started as assistance with a single pension decision quickly evolved into a continuing relationship, helping Sharon manage financial decisions she had previously depended on her husband to handle.
She said: “It’s quite nice that you’ve got… a second pair of eyes going over things and giving me that little bit of assurance. Because I say that’s how I would work with my husband, you know.”
Over time, Sharon said that support enabled her to feel more self-assured and knowledgeable about her finances: “I feel that that’s worked for me. I feel reasonably comfortable that I’ve got a better understanding of what the financial situation is like. I think by having a financial advisor, it gives me that bit of assurance that I’m not just looking at these figures, assuming everything’s okay, having to do further research to make sure the investments are okay.”
Don’t assume
Reflecting on her experience, Sharon believes it is vital not to presume everything will simply work itself out, and urges others to examine their pension arrangements, as she and her husband had not properly discussed their future plans and finances.
Sharon said: “We helped each other. The only thing that we made sure we did every year was we put £20,000 into an ISA. I’m very fortunate I get that. I have my pension coming in and I pretty much live on that. And I think if we’d had children, then we would have been looking at our finances differently”.
“It can be very easy, I think, to sit back and think, oh, everything will be okay. But I do think it is an extremely important aspect of people’s planning to make sure that they do have, I’m going to call it a bucket, but a pension to help you have the best sort of next phase of your life, if that makes sense, available to you.
“To have a health check, just go over what you’ve got, what that would look like in six months, six years. And is there anything that you can start taking or doing, putting in place now that will make that migration from a working life to a non-working life as easily and as maintainable as you possibly can because you know life is worth living.”
The pension checks couples shouldn’t put off
Marc Stewart, head of financial advice distribution at Skipton Building Society, is encouraging people to take the time to review their pension arrangements and discuss their finances with their loved ones.
Don’t leave pension conversations too late
Marc said: “Too often these conversations are delayed because people assume there is more time. Department for Work and Pensions research (2024) found nearly half of retired and semi-retired people only begin actively planning for retirement in their 50s. But a conversation that takes an hour or so today could save a loved one a great deal of stress in the future.”
Make a list of all workplace and personal pensions
Marc explained: “Many people are surprised by how many pensions they’ve accumulated through their working lives. The key question is whether your partner or loved ones would know where to find them if someone happened to them.
“Many couples have a broad understanding of their finances together, but not necessarily the details around pensions. This is because people build up pensions with different employers throughout their career, so it’s likely one partner won’t have full visibility.
“Knowing where to find key account information, policy documents and any details can make sure a huge difference if suddenly one partner had to manage everything alone. Many providers now communicate online, so if important paperwork is not shared through post, loved ones may struggle to find accounts without clear instructions. Ensure both partners know where pensions are held and how to access them if needed.”
Review beneficiary nominations
Marc said: “Couples should also regularly review beneficiary nominations. Circumstances may change over time, so it’s worth discussing with your partner your intentions, making sure that pension providers hold the most up-to-date information.
“Without an up-to-date nomination, there could potentially be delays while pension providers establish who should receive any benefits. It’s also an opportunity to discuss the role pensions may play as part of your wider estate planning and ensure your wishes are clearly understood. Keep these details current to enable a smoother transition for your loved ones.”
Discuss retirement income expectations and goals
Marc explained: “The best financial preparation isn’t always noting where pensions are, but having open conversations with your partner discussing your retirement income goals and expectations. This can look different from person to person, such as income needs or priority around supporting and spending time with family. Having these conversations regularly can help ensure you’re working towards a shared vision of retirement that’s achievable for both of you.”
Consider regular financial reviews and seek advice if needed
Marc said: “Checking in periodically can help identify any gaps and give you the opportunity as a couple to review plans together and make sure they’re still on track. For those who are unsure about their options and need additional support, like Sharon did, seeking financial advice can help provide clarity and confidence around decisions being made for the future.
“Sharon’s experience is a reminder that it’s important not to leave pension and retirement conversations until a life-changing event forces them. Taking time now to understand where your pensions are held, who your beneficiaries are and what your retirement plans look like can make a significant difference in the future.”
Skipton members are entitled to a complimentary one-hour Money Review to assist them in gaining a clearer picture of their financial situation, while those seeking more personalised guidance can also take advantage of Skipton’s regulated financial advice service. Further details are available via Skipton’s investment planning and advice page.